Most Malaysian drivers will have at least one minor collision: a tap at a traffic light, a scrape in a mall car park, a Myvi nosing into a car that braked late. The damage is usually small. What costs people money is the process afterwards, because two deadlines and one choice of claim decide whether you pay the excess yourself and whether you keep a No Claim Discount that took five years to build.
This guide is built from four official sources: the Bank Negara Malaysia (BNM) quick guide to motor insurance claims, which every insurer reproduces; PIAM's (General Insurance Association of Malaysia) motor insurance pages and its April 2026 towing statement; the PIAM and Malaysian Takaful Association *Jom, Level Up* guides to Knock-for-Knock claims; and the Financial Markets Ombudsman Service (FMOS) scope page. It explains the process. It is not legal advice, and your own policy wording decides the details.
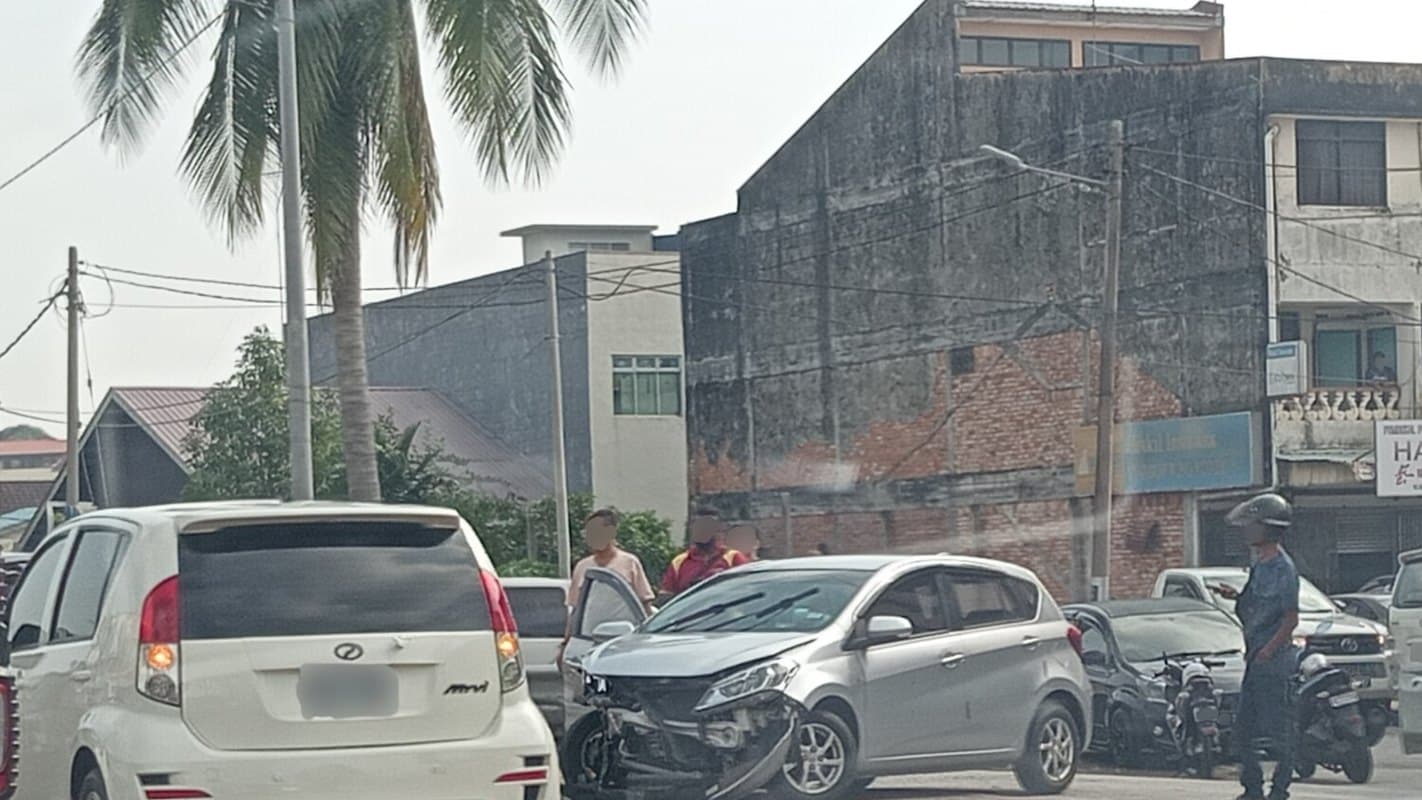
*Cover image: Danielrayyan09 / Wikimedia Commons (CC BY-SA 4.0), a damaged Perodua Myvi after a collision in Kluang, Johor.*
At the scene: five things to do
The BNM guide lists them in this order:
- Check it is safe before stepping out of the car, especially on a highway.
- Gather evidence. Note the place and time, photograph the scene and the damage to every vehicle, and exchange details with the other driver: licence number, phone number and address, car model and registration number, and insurer.
- Do not admit fault, agree to any offer or settlement, or sign anything. The guide says this in so many words.
- Call your insurer or its roadside assistance line if the car cannot be driven, and deal only with the authorised tow truck they send. Get the operator's name and registration number from your insurer first.
- Lodge a police report within 24 hours.
Towing is the step most likely to go wrong in 2026. On 13 April PIAM said rising costs had led to "potential service disruption or temporary suspensions" among tow truck operators. Insurers responded by prioritising stranded and accident cases, and some will reimburse an independent tow, subject to the policy terms. PIAM's advice is to ring your insurer before hiring anyone and to keep every official receipt.
The two deadlines
Police report, 24 hours. Section 52(2) of the Road Transport Act 1987 requires the driver of each vehicle in an accident to report it at the nearest police station "as soon as reasonably practicable and in any case within twenty-four hours". Police have said publicly that the offence applies even when both drivers agreed to settle privately. Without the report your insurer has nothing to start with, and the BNM guide warns that late reporting can bring a fine.
Insurer, 7 days. The BNM guide tells you to notify your insurer within 7 days of the accident and to submit the claim as soon as possible. Its list of ways to avoid a rejected claim puts this first, with complete documents second.
Which claim to file
There are three kinds of claim, and the right one depends on who was at fault and what cover you hold.
Own Damage Knock-for-Knock (OD-KFK). Use this if the other driver was at fault and you have comprehensive cover. You claim from your own insurer, which repairs your car at a panel workshop and later recovers the money from the other driver's insurer. PIAM lists the benefits: faster settlement, no need to appoint your own adjuster, and your NCD is untouched. The *Jom, Level Up* guide adds that the uninsured losses, meaning your excess and CART (Compensation for Assessed Repair Time, a daily allowance for taxi or rental costs over the days an adjuster says the repair should take), are paid by the other side's insurer. It works because every Malaysian insurer and takaful operator signed the Knock-for-Knock agreement of 18 March 1987, revised in June 2001.
OD-KFK does not apply when anyone was injured (whoever was at fault), when the other car is foreign-registered and insured outside Malaysia, or for commercial vehicles such as buses, taxis and hire cars.
Own Damage (OD). Use this when the accident was your fault. Your insurer pays for your repairs minus the excess, but the NCD goes back to 0% at your next renewal.
Third Party Property Damage (TPPD). This is the fallback if you are not at fault but cannot use OD-KFK, for example because you have third-party cover only. You claim directly from the other driver's insurer, appoint an adjuster, and submit their report and the repair bill yourself. BNM's figures show own damage claims take about two months from notification to payment on average, and third-party claims often take longer. To find out who insures the other car, the BNM guide points to the I-Search service at mycarinfo.com.my.
What the NCD is worth
PIAM publishes the private car NCD scale: 25% after one claim-free year, 30% after two, 38.33% after three, 45% after four and 55% after five or more. The discount comes off your basic premium.
Here is an illustration with a round figure. If your basic premium were RM2,000, a 55% NCD would cut it to RM900. After one at-fault Own Damage claim the NCD resets to 0%, so the next renewal would be the full RM2,000, and you would need five more claim-free years to get back to RM900. That is why it matters so much whether a not-at-fault accident goes through OD-KFK or a plain OD claim.
The documents
For an OD or OD-KFK claim, BNM's guide lists:
- Completed claim form
- Original police report
- Copies of the driver's and policyholder's IC and driving licence
- Copy of the vehicle ownership certificate
- Photos of the scene and the damage
- The police letter stating which party was compounded for a traffic offence
That last item is how fault is shown for OD-KFK. The police investigate the report and issue the compound, so follow up with the station where you reported until you have the letter. For a TPPD claim you also need the adjuster's report and the repair bill.
Two more charges catch people out. The excess is the part of each claim you pay yourself, whoever was at fault, though under OD-KFK it is recovered for you. Betterment applies to cars five years old or more: when a damaged part is replaced with a new original one, you pay a share of its cost based on the car's age, because the car ends up in better condition than before.
If the claim goes wrong
Complain to the insurer first, in writing. If you are unhappy with its final decision, the Financial Markets Ombudsman Service (FMOS), which replaced the Ombudsman for Financial Services (OFS), takes motor and third-party property damage disputes worth up to RM250,000. You must file within 6 months of the insurer's final decision. FMOS does not handle third-party bodily injury or death claims, or anything already filed in court. For general queries, BNM's guide also lists PIAM (03-2274 7399) and the Malaysian Takaful Association (03-2031 8160).