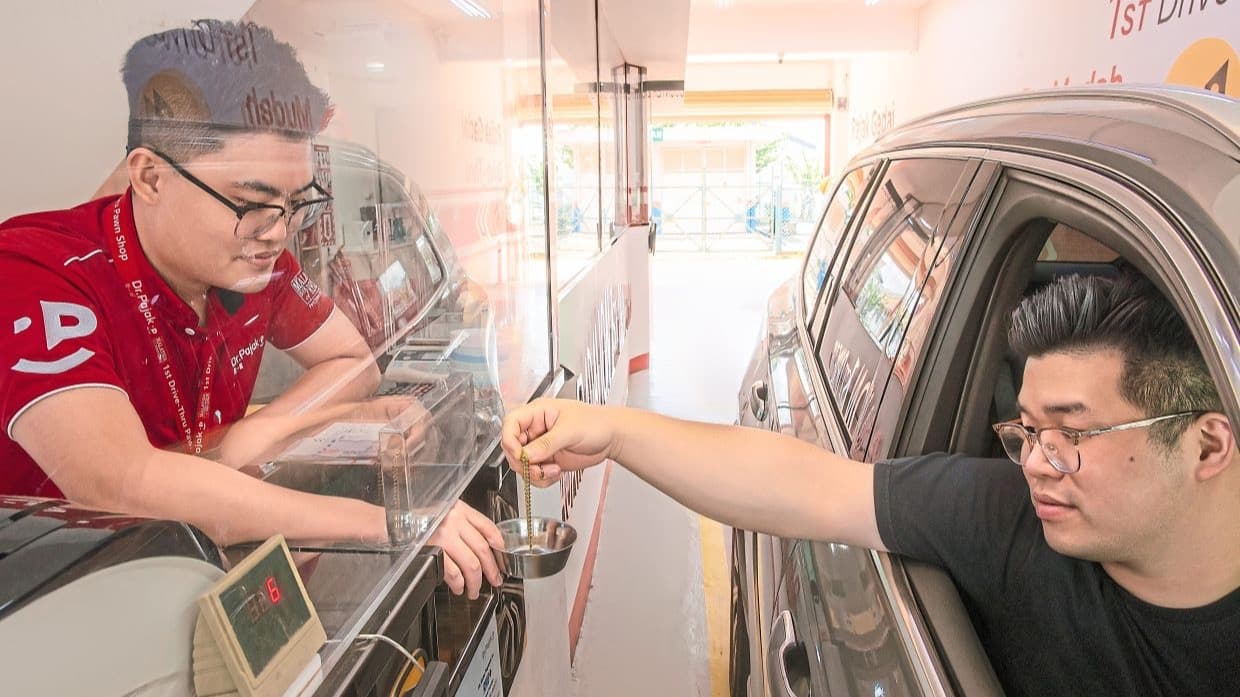
Pawning is one of the quickest ways to raise cash in Malaysia, with your own item as the only security. It is also governed by a short and fairly blunt law that most customers never read. These are the rules in the Pawnbrokers Act 1972 (Act 81) that decide what you pay and what you can lose.
What a licensed pawnshop can charge
Section 17 lets a licensee take profit only at the rate set by regulations, and it bars charging "any sum whatever" on the pawn beyond that. The ceiling the Housing and Local Government Ministry (KPKT) has stated publicly is 2% a month, or 24% a year.
On a RM3,000 loan, that cap works out to RM60 a month, or RM360 over a full six months. A service fee, valuation fee or storage fee stacked on top of the profit is what section 17 is written to stop. Ask to see how your figure was worked out before you sign.
Section 3 frames pawning around loans of up to RM10,000 on an article, so larger sums on gold usually point to a bank's Ar-Rahnu product instead.
The six-month clock and how to extend it
Section 18 gives you six months from the date of pawning, or longer if you and the shop agreed to that. Section 19 is the useful one. If you bring the ticket and pay the profit owed so far, the shop must extend the redemption period by at least three months when you ask. You don't need to repay the principal to do this.
Mark the date yourself. If you know you can't clear the loan by month six, paying the profit before the deadline keeps the item out of the next step.
What happens if you don't redeem
Section 23 splits unredeemed items by the amount you borrowed, not by what the item is worth.
- Pawned for RM200 or less: the item becomes the pawnbroker's property. There is no auction and no surplus, even if the gold is worth several times the loan.
- Pawned for more than RM200: it can only be disposed of by public auction, run by a licensed auctioneer. The shop itself may bid.
If the sale brings in more than the loan and profit, section 25 says the shop has seven days to send you a statement and notice by registered post, to the address in its book. You then have four months from that notice to claim the surplus. So tell the shop if you move house. Within four months of the auction you can also ask to inspect the sale entry and the auctioneer's signed catalogue (section 24).
After those four months, unclaimed money goes to the Accountant General within 14 days (section 26). You can still claim it from the Treasury by proving you are the owner (section 27).
Shops can't skip this by putting forfeited gold in a display case. In 2023 the Court of Appeal upheld the conviction of Kedai Pajak Shin Ngien Sdn Bhd, fined RM5,000, for selling unredeemed gold at its pawn premises, because section 16(3) confines licensees to pawnbroking.
Theft, fire and the 125% rule
Section 22 makes the pawnbroker responsible for loss or damage, including from fire, theft and robbery. But the compensation has a catch. The pledge's value is assumed to be one quarter more than the loan. If you borrowed RM3,000 on a chain worth RM5,000, the assumed value is RM3,750. A magistrate can separately order "reasonable compensation" on a complaint, but that isn't automatic. The lower your loan relative to the item's value, the larger the gap, so keep your own photos and receipts for valuable pieces.
Your ticket is the key
Section 18 obliges the shop to hand over the pledge to any person who presents the ticket and pays. Guard it like cash.
- Lost ticket: apply to the shop for a copy of its book entry, which it must give free and without delay. It must then refuse to release the item to anyone presenting that ticket for seven days. A magistrate can order delivery or a new ticket (section 21).
- Selling your ticket: those "we buy pawn tickets" offers are a trap for the buyer and a warning sign for you. Section 41 makes purchasing a pawn ticket an offence, with a fine of up to RM20,000 or 12 months' jail.
- Pawning for someone else: pawning another person's item without their authority carries up to RM50,000 or two years' jail (section 28).
Shops can't accept pledges between 6pm and 8am, or from anyone under 18 (section 16).
Spotting an unlicensed operator
KPKT has said licensed premises display a "Pemegang Pajak Gadai Berlesen" signboard, use stipulated forms and can be looked up on its i-Gadaian app, and that overcharging should be reported to the ministry. We could not confirm the app is still current this run, so check with KPKT if it won't load. Police warned in 2021 against online pawn offers, and said pawning should be done in person at registered premises. Running without a licence is punishable by a fine of RM20,000 to RM100,000, up to five years' jail, or both (section 7).
How Ar-Rahnu differs
Section 46 exempts licensed banks and registered co-operatives from the Act. That means the 2% cap, the RM200 rule and the section 25 surplus notice don't bind them. Their contract does, so read it. Not every Ar-Rahnu counter is a bank or co-operative, so ask which rules apply to yours. Published terms we checked:
- Bank Muamalat: fixed 11.25% a year (0.9375% a month) on the financing amount, up to 80% of the gold's current value, RM250 to RM500,000, up to 18 months.
- TEKUN Ar-Rahnu: RM0.50 per RM100 of the gold's value, up to 80% margin, RM100 to RM300,000, six months with extensions, and a 15-day minimum charge. Its page doesn't spell out the billing period, so ask. It says any surplus after sale and costs is paid to you.
Note the difference in base: one charges on the money you borrow, the other on the value of your gold. Compare the ringgit quote for your own item, not the headline rate.
The comparison table below sets the two systems side by side.