MetMalaysia says the northeast monsoon started on 27 October 2026 and expects three to five episodes of continuous heavy rain between November and January. Our flood warnings guide covers the alerts and the river levels. This one is about the morning after: who pays.
The short version is that a lot of people will find out it isn't their insurer. Bank Negara Malaysia said this year that roughly two-thirds of the estimated losses from the 2021 floods, around RM4 billion, were not insured. The Department of Statistics counted RM636.9 million in flood losses for 2025, including RM183.8 million on homes and RM6.8 million on vehicles.
Comprehensive does not mean flood
Standard private car wordings exclude damage from flood, storm, landslip and other convulsions of nature. Flood damage is only payable if the Special Perils extension is on your policy. PIAM, the general insurers' association, says to look at the "Additional Coverage" line on the schedule. PIAM describes that extension as an option on comprehensive cover. Its description of Third Party, Fire and Theft covers your own car for fire and theft only.
Having the words "Special Perils" on that line still doesn't settle how much you get, because the add-on varies:
- MSIG sells a full version and a limited one. The limited version is capped at 25% of the total sum insured, so RM15,000 on a car insured for RM60,000.
- RHB AutoMax has full Special Perils on the Pro plan and none on Lite.
- SOMPO says its motor policies include it, up to 100% of the sum insured.
Price is usually a percentage of the sum insured. Motorist put it at 0.20% to 0.50% in August 2026, which is RM90 to RM225 a year on a RM45,000 Myvi, and PIAM's own example was about RM42 a month on a RM100,000 car. Generali says it can be added mid-term, which is worth asking your insurer about now rather than at renewal.
The NCD question nobody agrees on
Search this and you will get opposite answers. CariCarz says a Special Perils claim will not reset your No Claim Discount. BJAK, Qoala and Pos Malaysia's guide say it will. So we read an insurer's terms. Generali says NCD falls to zero at the next renewal after a claim. Its exception needs you to be not at fault, with an identifiable and insured offending vehicle. A flood has no offending vehicle, so on that wording the reset applies. Other insurers' wordings may differ, which is why you should ask yours in writing.
It matters on small claims. Take a car with a RM2,000 premium before NCD and a 55% discount, paying RM900. Assume the premium stays flat and you lose the discount. Generali's ladder climbs back through 0%, 25%, 30%, 38.33% and 45% before returning to 55%. That costs you RM1,100, RM600, RM500, RM333 and RM200 over five renewals: about RM2,733 in lost discount. On that example, a RM2,000 carpet and seat job would cost more than it pays. An engine rebuild or total loss would not. Do this sum with your own numbers. NCD relief add-ons exist (Generali prices its at 15% of the NCD entitlement, minimum RM50), but read when they end.
If your car is in the water
- Get out first. Turn the engine off, move to higher ground and call for help. A car can be replaced.
- Do not start it afterwards. Malay Mail's guide warns against it if water passed halfway up the wheels, since it can damage the engine control unit. Water can also be drawn into the engine.
- Photograph everything. Include the waterline, the street and the plate, with the date and time.
- Call your insurer's 24-hour line before any tow. PIAM said in April 2026 that towing disruptions meant priority for stranded and hazardous cases, with towing from homes scheduled. Some insurers reimburse an independent tow, subject to your terms, so check first and keep receipts.
- Ask about the police report. PIAM's advice is to lodge one as soon as possible, ideally within 24 hours, unless waived in exceptional cases. Insurers can waive it after a major flood, but let them tell you that.
- Expect two deductions. Betterment can apply on cars aged five years and above when old parts become new ones. For a total loss, agreed value pays the set figure, and market value pays the car's depreciated worth at the time.
Your house: three policies, three answers
PIAM says a basic fire policy often excludes floods and windstorms unless you pay extra. If the only cover you remember is the one that came with your housing loan, check it first. Houseowner policies cover the building and householder policies cover contents. Generali's Home Protector, for example, lists flood under both, but with an excess on flood claims. BNM says flood is commonly an optional add-on on home cover, so read yours rather than trusting the product name.
Strata homes: section 93 of the Strata Management Act 2013 is cited as requiring the management body to insure the building. Ask it for the schedule, see whether flood is listed, and assume your furniture is your own problem.
Under-insurance is the quiet one. Generali says that if the sum insured is below actual value, you are treated as insuring the difference yourself. As an illustration, insure a RM400,000 rebuild for RM200,000 and a RM50,000 flood loss could pay about RM25,000. PIAM says to insure on rebuilding cost, not market value, and it runs a free Building Cost Calculator.
For the claim itself, PIAM's list is a police report, claim form, proof of ownership, photos, repair quotations and an inventory of damaged contents with brand, model, serial number and value. It also warns to get written approval before any repair, including emergency work, because unauthorised work may not be covered. Photograph the damage before you clean up.
If you have no cover, or the insurer says no
- Bantuan Wang Ihsan: RM1,000 to the head of an affected household, claimed through MyIBJKM by scanning a QR code at an evacuation centre. The flood warnings guide has the limits. NADMA's rules were last read there on 26 October.
- A rejected claim: complain to the insurer in writing, then take its final decision to the Financial Markets Ombudsman Service within six months. FMOS's scope page lists motor claims up to RM250,000. It does not list fire or home policies, so ask FMOS or Bank Negara where a house dispute should go.
- Next year: BNM points lower-income households to Perlindungan Tenang products at about RM50 to RM75 a year. Only some include flood cover, so check the product sheet.
*Sources read on 4 November 2026 unless stated: DOSM's 15 April 2026 flood statement; Insurance Business's 4 February 2026 report of BNM's comments; PIAM's motor page, its 13 April 2026 towing release, and its 3 December 2024 flood release as hosted by Zurich; PIAM's houseowner advisory on InsuranceInfo.com.my; MSIG, RHB, SOMPO and Generali's published add-on and FAQ pages; Generali's Home Protector disclosure sheet; FMOS's scope page; Motorist (10 August 2026); Malay Mail (14 March 2022); PropertyGuru on section 93, which we did not check against the Act's text. PIAM's RM42 example comes from its November 2025 monsoon note, read in September, and that page has since moved. This explains how the products work and is not financial advice. Your own policy wording decides the claim.*
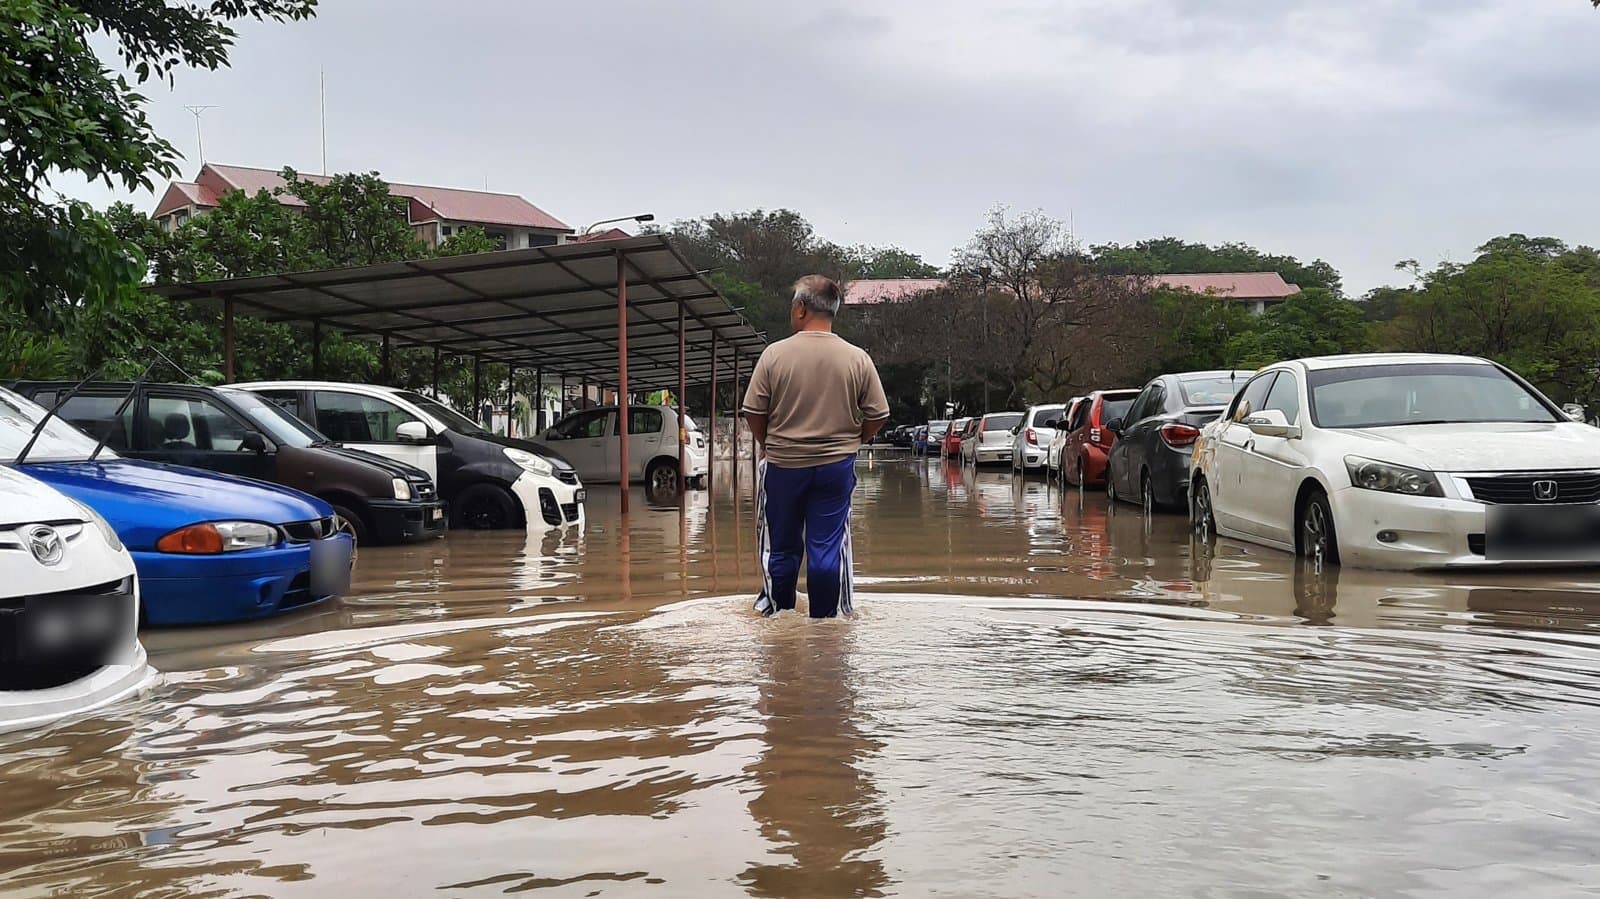
*Cover image: Xrchr / Wikimedia Commons (CC BY-SA 4.0), flooded car park at Section 24, Shah Alam, December 2021, cropped with number plates blurred.*